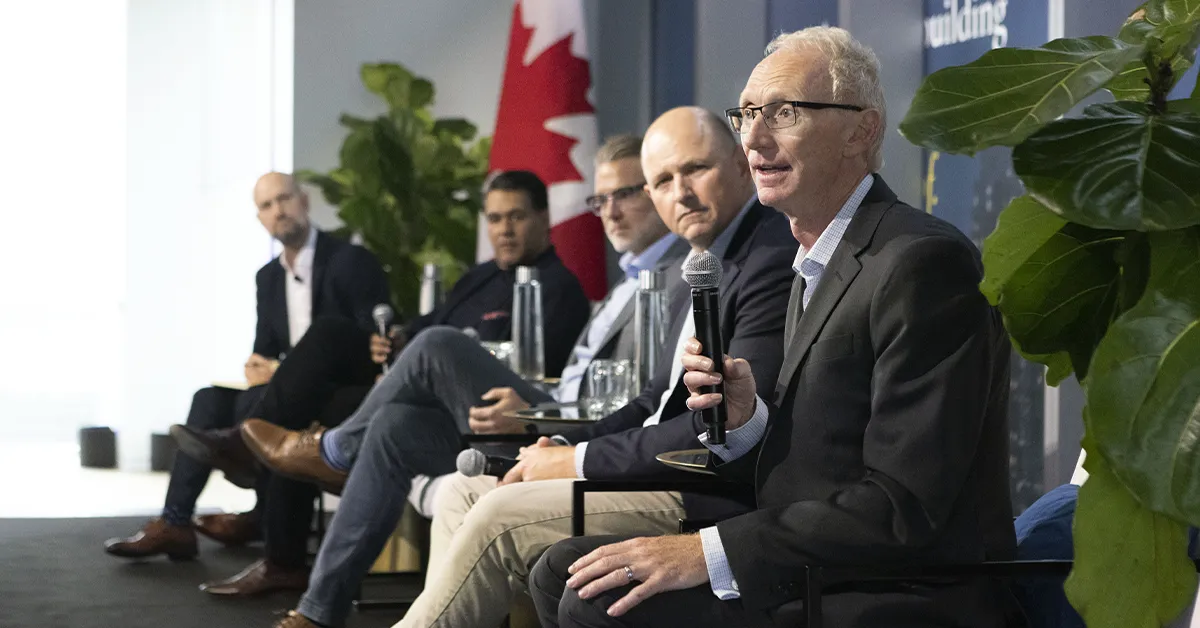
Against the backdrop of Canada's most significant energy and infrastructure expansion in decades, Dokainish BUILD '26 brought together leaders from district energy, long-duration storage, nuclear generation, and project finance to discuss how the country can balance growth with long-term resilience. I had the opportunity to join the panel "What's Next for Canada's Energy and Infrastructure" alongside Carlyle Coutinho, CEO of Enwave; Jon Norman, President of Hydrostor; Jack Tasker, VP Finance of Bruce Power; and Annette Verschuren, Chair and CEO of NRStor. Our discussion covered trade and supply chain pressures, capital formation, regulatory clarity, and the collaborative culture that distinguishes Canada's approach to building major projects.
Here are the key takeaways:
Capital is available – but only for projects that can be delivered
Trade dynamics are reshaping cross-border investment patterns, and Canada stands to benefit from the shift. At the recent Canada Investment Summit, international investors from countries such as Norway and the U.K. actively sought to understand Canada's infrastructure landscape and identify where they can participate. Global investors are now differentiating Canada from the United States in their allocations. The message was straightforward: capital is available for projects that can be delivered.
Delivering them, however, requires long-term planning. The power sector requires long lead times to develop projects, is capital-intensive, and its assets take years to build. Nuclear plants take 10 to 12 years. Gas turbines currently have lead times of at least five years. In the West, Saskatchewan and Alberta are transitioning from coal to nuclear, targeting a 2035 to 2040 timeframe. In the East, conversations are advancing around interconnecting the Atlantic provinces and managing the power coming out of Newfoundland.
Compounding the challenge is uncertainty around future demand, which developers cannot manage on their own. Demand curves shift constantly, driven by data centers, the electrification of buildings and vehicles, and economic cycles. The growth potential in power demand, amplified by AI, has accelerated attention to these issues, yet it still takes years to bring any project to fruition.
Collaboration is Canada's real competitive edge
Meeting the country's energy needs will require a grid built for both redundancy and flexibility. The country's energy needs cannot be met by any one source – solar, wind, gas, nuclear, and hydro each have a role to play. In the West, strong wind resources warrant significant development, alongside natural gas. In the East, there is greater technological capability around nuclear. Ontario is starting to make progress with long-lead-time procurements that provide the contracts needed to bring financing to the table.
Canada's collaborative culture is a real differentiator. The Calgary oil patch is a market leader in technology and advanced drilling, an intellectual resource well regarded around the world. That collaborative instinct is a meaningful advantage Canada should leverage more deliberately. Partnerships such as deep lake water cooling have worked for 25 years, and what sustains them is not contracts but trust. On the nuclear side, the close collaboration between Ontario's two major operators, OPG and Bruce Power, on refurbishments has delivered rare success in an industry where it is uncommon. The two operators share lessons learned, staff, and coordinated schedules.
Areas for improvement remain. Innovation is one: the safety culture in nuclear creates a natural hesitation, but refurbishments are ripe for automation. Affordability, ultimately, is the biggest question the industry must address.
Canada needs to accept more risk to get things built
For those approaching capital providers, the key is to understand what kind of capital is needed, because capital comes in a wide variety of forms and risk profiles. This discipline extends to project preparation more broadly. A project with long-term off-take contracts or power purchase agreements, will attract a different capital profile than one without the same contractual support.
The broader challenge is that Canada needs to accept more risk to get things built. The market is small, and companies that succeed here must export to scale. There is also a lingering hesitation around private-sector involvement in public goods, which is critical in the power sector. There are many examples of successful private capital deployment in the industry; the greater risk is not building at all.
The capital is available, the collaborative culture is a proven advantage, and the demand is real. The question is whether Canada can translate planning into execution quickly enough to seize the moment.